Loading
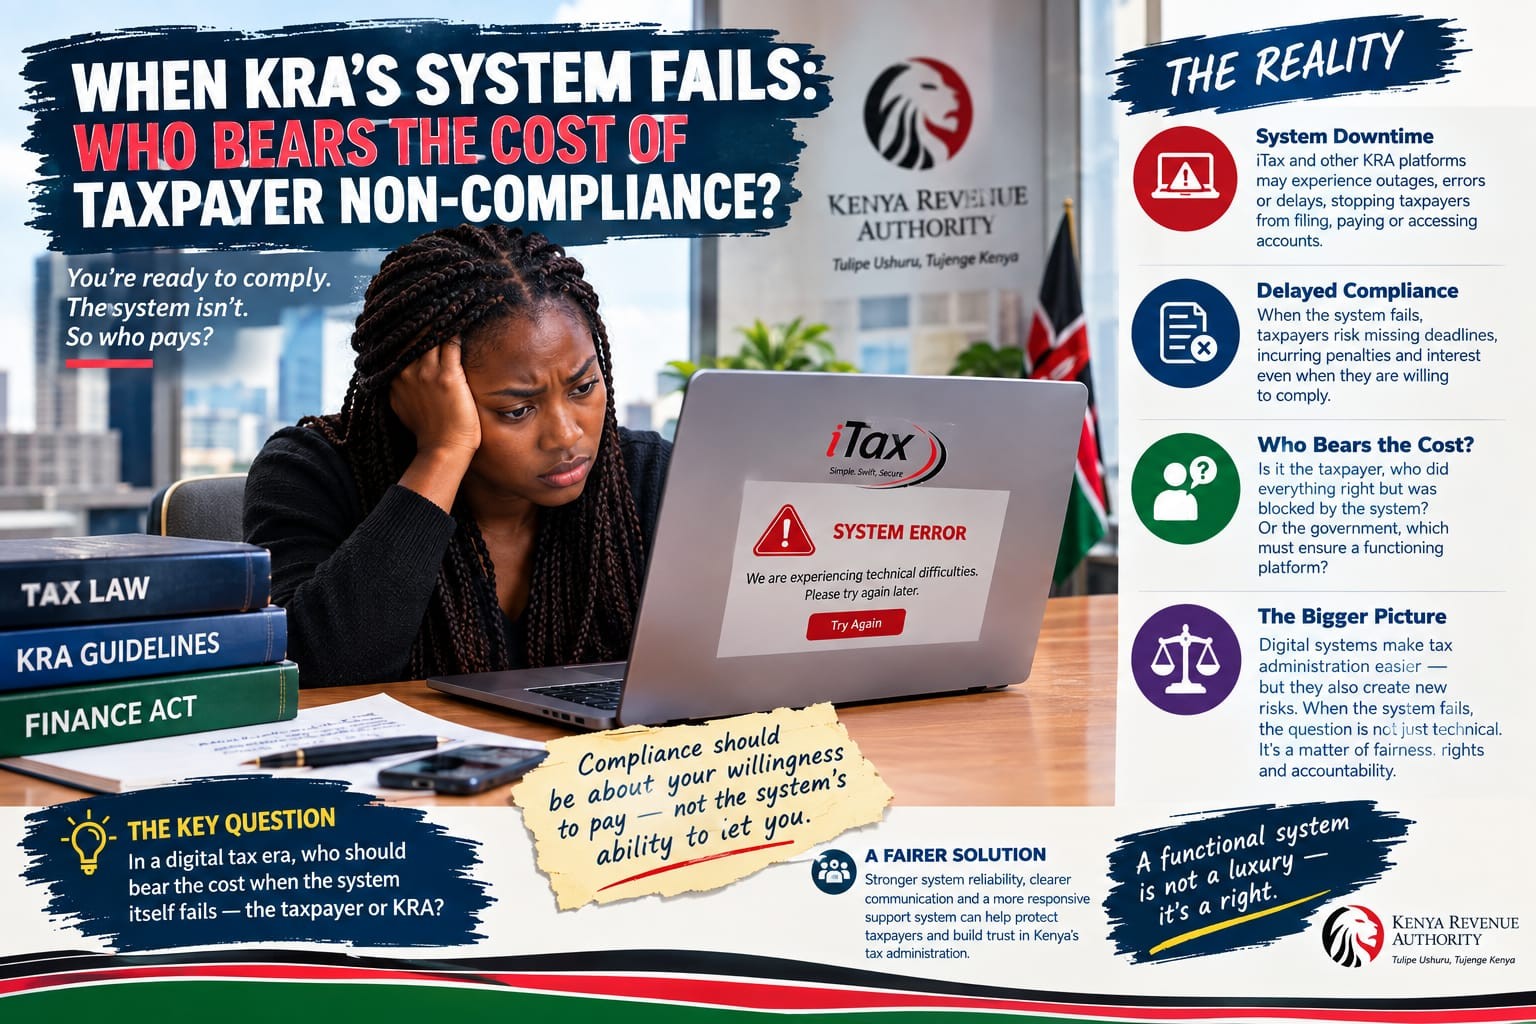
“What happens when a taxpayer is ready to comply, but the system will not let them?”
Kenya’s tax administration is increasingly digital. Filing returns, making payments, accessing tax credits and managing tax obligations now depend heavily on electronic platforms such as iTax. Digitalisation has made tax administration faster and more centralised, but it has also created a new question of accountability: who bears the cost when the system designed to facilitate compliance becomes the very obstacle to compliance?
The question became particularly relevant in September 2026 when the Kenya Revenue Authority (KRA) acknowledged intermittent downtime on the iTax portal. The disruption affected return filing and payment services at a time when taxpayers were working towards statutory deadlines. KRA subsequently announced that penalties and interest attributable to verified system downtime during September would be waived pursuant to section 89(5A) of the Tax Procedures Act.
The announcement may appear to be a practical response to a technical problem. Legally, however, it raises a broader issue: can a taxpayer fairly be penalised for failing to comply with an obligation where the tax administration's own digital infrastructure prevented that compliance?
When the system becomes the obstacle.
Tax compliance is not merely a matter of imposing obligations on taxpayers. It also requires an effective administrative framework through which those obligations can reasonably be discharged.
This is particularly important in an environment where taxpayers are increasingly required to interact with KRA electronically. When the portal is inaccessible, a taxpayer may be unable to file a return, make a payment, utilise an approved credit or complete another statutory process. The resulting non-compliance may therefore have little to do with unwillingness to comply.
Section 89(5A) of the Tax Procedures Act provides an important statutory mechanism for dealing with this problem. KRA's September 2026 notice demonstrates that the provision is not merely theoretical: it can operate as a safeguard where penalties or interest arise from verified failures in the electronic tax system.
But the issue extends beyond temporary outages
A recent Tribunal decision offers another perspective.
The Tax Appeals Tribunal recently confronted a related question in Howard Humphreys (East Africa) Limited v Commissioner of Domestic Taxes [2026] KETAT 295 (KLR).
The taxpayer had approved overpayment adjustment vouchers that could lawfully be used to offset its tax liabilities. However, when it attempted to use the approved credits to settle PAYE liabilities, the relevant iTax functionality had been disabled. The taxpayer subsequently incurred interest of Kshs. 151,642.30 on the affected PAYE liabilities.
The Tribunal ultimately held that the taxpayer was entitled to utilise the approved overpayment adjustment vouchers and set aside the Kshs. 151,642.30 interest that had accrued.
The significance of the decision lies not simply in the amount of interest involved. It illustrates a broader principle: where a taxpayer is legally entitled to use a particular mechanism to meet a tax obligation, an administrative or technological barrier should not automatically transform that taxpayer into a defaulter.
The Tribunal's reasoning is particularly relevant to an increasingly digital tax environment. A taxpayer can be willing and able to pay, yet still be prevented from doing so because the relevant functionality is unavailable.
Technology cannot eliminate administrative fairness.
Kenya's Constitution requires public administration to comply with principles of legality, reasonableness and procedural fairness. Article 47, together with the Fair Administrative Action Act, provides an important framework within which decisions and actions of public bodies are assessed.
Digitalisation does not remove these obligations.
If anything, greater reliance on technology makes administrative accountability more important. A taxpayer cannot physically walk around an unavailable digital function. If iTax does not permit a taxpayer to complete a transaction, the taxpayer has limited alternatives unless KRA provides another effective mechanism.
This is where Howard Humphreys becomes particularly instructive. The Tribunal observed, in effect, that it would be unfair to impose interest on liabilities that the taxpayer stood ready and legally entitled to settle through an available statutory mechanism, but could not do so because of the administrative position taken by KRA.
The question therefore becomes bigger than whether an online portal is functioning. It becomes a question of administrative responsibility.
But taxpayers still have a responsibility.
None of this means that every late filing can simply be attributed to iTax.
Evidence matters.
A taxpayer who encounters a genuine system problem should preserve screenshots, error messages, system-generated notifications, support tickets, emails, payment attempts and other records showing when and how the failure occurred.
This distinction is important because KRA's September 2026 waiver is expressly tied to verified periods of system downtime. It does not mean that every penalty appearing on a taxpayer's ledger during September will automatically disappear.
The taxpayer therefore still has a duty to act diligently. Where possible, the taxpayer should attempt to comply, seek assistance through the available channels and create a clear documentary trail demonstrating that the failure was caused by the system rather than inaction.
From digital compliance to digital accountability.
There is an important lesson emerging from Kenya's evolving tax administration: the digitisation of tax compliance must be accompanied by the digitisation of accountability.
When taxpayers are expected to file electronically, pay electronically and maintain their tax affairs through electronic platforms, the reliability of those platforms becomes part of the compliance environment itself.
The September 2026 iTax disruption provides a timely example. KRA's decision to waive penalties and interest attributable to verified downtime recognises that taxpayers should not bear consequences arising from a failure they could not reasonably control.
The Howard Humphreys decision adds another dimension by demonstrating that technological or administrative barriers can have direct financial consequences for taxpayers and that those consequences may, in appropriate circumstances, be capable of challenge.
The future of tax administration may therefore depend on more than simply making tax systems digital. It will require systems that are accessible, reliable, transparent and capable of recognising when the failure to comply was not the taxpayer's fault.
The takeaway for taxpayers.
When the system works, comply.
When the system fails, document it.
And when a taxpayer can demonstrate that a failure to comply was directly attributable to the tax administration's own system or administrative action, the resulting penalty or interest should not simply be accepted without examining the legal basis for imposing it.
In an increasingly digital tax environment, compliance cannot be a one-way street.
If taxpayers are expected to comply through the system, the system must also be accountable when it prevents compliance.